Chime® – Fee-Free Banking

- 239.01K Reviews
- 4.7
- Downloads
- 10,000,000+
 Analysis by Mobxio
When I try a new money app, the first few days are rarely the hard part. The real test is whether it still helps once the novelty wears off and ordinary bills, paydays, and spending routines take over. Chime – Mobile Banking is a finance app from Chime, and its appeal is straightforward: it brings everyday banking tasks onto a phone and aims to reduce some common fee and timing frustrations.
Its early appeal comes from a low-friction setup and a clear set of reasons to try it. Chime is free to download, is rated for Everyone, and has a 4.7 average across around 946,000 ratings. With over 10 million installs, it is already a familiar option in mobile banking. Those figures can suggest broad interest, but they do not tell me whether the account fits a particular person’s pay schedule or cash habits; that depends on how you use it week to week.
From first-week convenience to an everyday routine
I look at Chime’s first-week convenience as the start of a practical test, not the whole story: the useful question is whether its phone-based banking fits the moments when money actually moves. I’d pay attention to what I check most often and which alerts help me act, then see whether those habits still feel worthwhile once the new-account excitement fades. From there, the focus shifts to the routine value it can offer month after month.
Getting started without a branch visit
First things first, setting up Chime – Mobile Banking is a breeze. You download the app, sign up, and boom, you’re ready to roll. No need to visit a branch or deal with any of that old-school paperwork. As someone who's not a fan of red tape, I found this incredibly refreshing.
That phone-first approach is useful if you handle most money tasks digitally and do not want to plan around branch hours. It is less compelling if you depend on in-person help, prefer discussing account questions face to face, or often need to deposit cash in a way that suits your routine. Before moving your main banking over, I’d think through how you receive money, pay regular expenses, and get support when something goes wrong. A smooth sign-up is only the beginning; the account needs to work for the less convenient parts of real life, too.
Chime’s current version is 5.301.0, and the app’s core purpose is not to replace every financial tool at once. I would treat it as a candidate for the account you use for recurring income and day-to-day spending, then judge it by whether its routine tasks feel manageable. That is a more useful test than simply asking whether the interface looks modern during the first session.
Features that matter after the first payday
Let’s talk features. Chime offers a fee-free banking experience. That means no monthly maintenance fees, no overdraft fees, and no foreign transaction fees. I mean, seriously, who enjoys paying fees? It’s like finding out your favorite snack has zero calories – pure joy!
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
The practical value of avoiding a monthly charge is easiest to see when an account would otherwise sit quiet between paychecks. It can also make the app appealing as a place to route everyday spending without having to keep a minimum balance just to avoid a maintenance fee. Still, “fee-free” should not become shorthand for “every banking situation is free.” I’d read the current account terms before relying on any service, especially if a transaction involves another provider or a special circumstance. The useful habit is to check the details before a need becomes urgent.
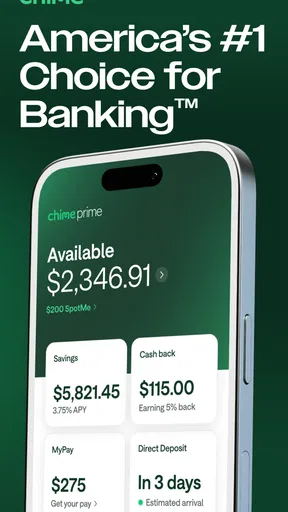
Another cool feature is the SpotMe option. This allows you to overdraft your account up to $200 without any fees. It’s like having a friend who’s got your back when you’re short on cash. And did I mention you get paid up to two days early with direct deposit? It’s like payday comes with a fast-forward button!
These benefits are helpful, but I would not build a budget around the assumption that an overdraft cushion is extra income. A more dependable use is as a temporary buffer for a small timing mismatch, such as a routine purchase landing shortly before a deposit. If you regularly need that cushion to cover essentials, the app cannot solve the underlying gap between income and expenses. Likewise, early access to direct-deposit money can make a deposit available sooner, but it does not increase the amount you earn or make future bills disappear. I’d keep recurring payments aligned with the date money is reliably available to me, rather than treating an early arrival as guaranteed breathing room every month.
That distinction is one reason Chime may suit someone who wants a convenient spending account better than someone looking for a full financial plan. It can help with access and everyday account awareness, while choices such as how much to save, when to pay bills, and how to handle irregular income still need attention from the user. I find that separation healthy: a banking app can make a routine easier, but it should not be mistaken for a substitute for one.
Small money-management habits that can stick
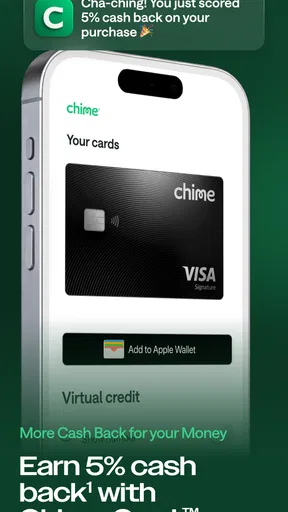
Managing your money with Chime is as easy as pie. The app provides real-time transaction alerts, so you always know what’s going on with your account. Plus, you can block your card directly from the app if it goes MIA. Talk about peace of mind!
Alerts become more useful when I treat them as a quick review rather than background noise. If a purchase notification looks unfamiliar, I can pause and check the account instead of discovering it much later. But turning on every notification can also make a phone feel busier, so I’d keep the alerts that help me act—especially transaction activity—and avoid letting repeated pings become something I automatically dismiss. A notification is a prompt to inspect, not a guarantee that every issue resolves itself.
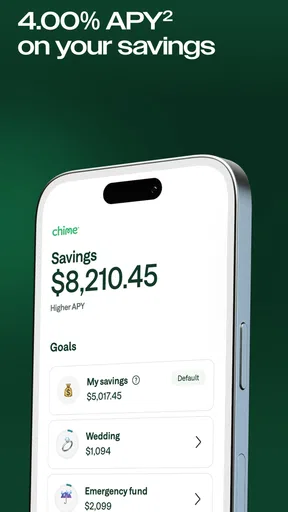
On top of that, there’s an automatic savings feature that rounds up your purchases to the nearest dollar and transfers the difference to your savings account. It’s like your own little magical piggy bank.
Round-ups are best understood as a small, automatic nudge, not a savings plan on their own. They may suit someone who finds it easier to save through tiny actions than through a large scheduled transfer. One practical way to assess the feature is to let it run alongside a normal spending routine and then check whether the transfers feel comfortable. If a tight week makes every purchase count, I would rather make a deliberate choice about saving than let an automatic extra transfer surprise me. The convenience is real, but so is the need to keep an eye on the cash left for essentials.
A realistic routine might look like this: I receive a direct deposit, use the account for groceries and regular purchases, and rely on alerts to notice activity as it happens. A card-blocking control is reassuring if I misplace the card while out, and round-ups can create a small savings habit in the background. The key is to check the account before bills are due and leave enough available for them. That routine uses several parts of the app together without pretending that any one feature will manage the whole budget for me.
Where the convenience has limits
Now, not everything is sunshine and rainbows. While the app is generally smooth and user-friendly, there were a few times I noticed some lag. Also, because it's fully online, if you’re someone who likes the idea of walking into a physical bank, this might take some getting used to.
That online-only trade-off affects more than preference. If an issue needs attention at an inconvenient moment, there is no branch visit to fall back on, so I would want to feel comfortable handling account tasks through the app and its available support channels. The occasional lag also matters most when I need to check a balance quickly or act on an account prompt. It may be only a passing annoyance, but anyone who relies on immediate access should test the app in ordinary conditions before making it their only way to manage money.
Compared with a traditional bank account, Chime puts the phone-based routine and reduced monthly-fee friction at the center, while a conventional branch-based option may be more reassuring to someone who values face-to-face service. Compared with other mobile banking choices, I would not choose on a catchy benefit alone. I’d compare how each option fits my direct deposit, recurring bills, cash needs, and preferred support style. The best alternative is the one that handles the unglamorous basics reliably for you, not necessarily the one with the most appealing first-week feature.
Chime is also not an obvious fit for someone who wants one app to provide extensive in-person banking or who dislikes managing money through a phone. Nor would I recommend choosing it solely because early pay sounds attractive: if a person’s income is irregular, the more important question is whether the account’s day-to-day tools and timing fit that pattern. For someone who already handles finances digitally and wants a straightforward place for routine deposits and spending, the balance may look different.
Keeping it useful without adding financial noise
The best way I can see to keep Chime useful month after month is to give it a defined job. For example, I might use it for regular spending and savings round-ups while keeping a separate account for a different purpose. That split can make transactions easier to interpret, but it also means checking more than one place and remembering which account pays which bill. A second account is only helpful if the extra organization is worth that maintenance.
I would also review recurring payments after changing where income lands. Moving a deposit is not the same as moving every payment, and overlooking an old payment route can create avoidable confusion. A simple personal checklist—income, rent or housing payments, utilities, subscriptions, and any scheduled transfers—helps me confirm that the new arrangement matches my actual calendar. This is not a special feature; it is the small bit of setup that makes mobile banking feel dependable later.
Chime is free, which lowers the barrier to trying it, but switching your financial routine still has a cost in attention. I would not rush to close an existing account just because the app feels easy during sign-up. First I’d use the new setup for ordinary purchases, verify that deposits and scheduled expenses behave as expected, and then decide whether it deserves a larger role. That gradual approach is especially sensible for anyone who depends on a single account for essentials.
People often wonder whether early payday means they can count on a fixed earlier date, or whether SpotMe should be treated as a regular overdraft allowance. I would make plans around the actual deposit timing and account terms I can see, not around a best-case expectation. The same goes for savings round-ups: they are an automatic convenience, but they do not remove the need to make sure the balance covers bills. Thinking in terms of “helpful tools, not promises” keeps the app’s benefits in perspective.
Another useful question is whether Chime can replace a bank that someone already likes. My answer is: only if its digital-first approach suits that person’s habits and the practical details line up. If branch access is important, if cash handling is central to daily life, or if a human conversation is the preferred way to resolve account problems, a traditional alternative may be a better match. If those needs are rare and phone-based banking already feels natural, Chime has a stronger case.
Does it earn a lasting place?
But honestly, these are small potatoes in the grand scheme of things. The convenience and features that Chime offers are truly game-changing for anyone looking to simplify their banking experience.
After the first-week appeal fades, the lasting value comes down to whether the app supports habits you already want: checking transactions, keeping an eye on spending, and saving small amounts without making each action a separate chore. For me, that is a more convincing reason to keep using a banking app than novelty alone. The trade-off is a fully online relationship and a need to stay engaged with the account rather than assume that convenience handles every financial decision.
Chime was released on March 28, 2014, and the app’s continued presence in mobile banking makes it a familiar choice rather than a brand-new experiment. Its age rating is Everyone, and it remains free to use as an app. I would still make the decision based on the current account terms and my own routine, not its popularity or how long it has been around. A widely used app can be a sensible option, but personal fit is what determines whether it earns a lasting place on my phone.
In conclusion, if you’re tired of the traditional banking rigmarole and want something that’s straightforward, user-friendly, and comes with a load of perks, Chime is definitely worth checking out. It’s like the cool, tech-savvy friend you never knew you needed in your financial life.
My recommendation is strongest for someone who wants to manage routine banking digitally, appreciates transaction alerts, and values a fee-conscious setup without expecting the app to replace budgeting judgment or in-person support. If that sounds like your everyday life, it is worth considering. If you need a branch, prefer more hands-on service, or would find automatic saving and deposit timing hard to plan around, compare it carefully with the bank you already use. That is the difference between an appealing first impression and a banking routine that still works months later.
Chime® – Fee-Free Banking FAQ
Is Chime – Mobile Banking safe to use?
Yes, Chime is designed with security in mind. It uses encryption to protect your data and secure your transactions. Additionally, Chime is FDIC-insured up to $250,000 through its banking partners, ensuring your money is protected. The app also offers real-time alerts for every transaction, keeping you informed and secure.
Does Chime charge any fees for its services?
Chime is known for its fee-free approach. There are no monthly maintenance fees, no overdraft fees (up to a certain limit), and no international transaction fees. However, fees may apply for cash deposits at certain locations or using out-of-network ATMs, so it's important to review their terms for full details.
How do I deposit money into my Chime account?
Chime offers several ways to deposit money into your account. You can set up direct deposit from your employer, transfer funds from an external bank account, or deposit cash at over 90,000 retail locations using third-party services. Additionally, mobile check deposit is available for eligible members.
Can I use Chime for direct deposits and early paydays?
Yes, Chime supports direct deposits and offers an early payday feature. With direct deposit, you can receive your paycheck up to two days earlier than traditional banks, depending on your employer’s payment schedule. This feature is particularly beneficial for those who want quicker access to their funds.
What should I do if I lose my Chime card?
If you lose your Chime card, you should immediately disable it via the Chime app to prevent unauthorized transactions. After disabling, you can order a replacement card directly within the app. Chime provides support to guide you through the process and ensure your account remains secure.
The Best Parts of Chime® – Fee-Free Banking
Things to Keep in Mind About Chime® – Fee-Free Banking